Be your own CFO.

Financial statements for your household, a 50-state tax engine and a lifetime retirement optimizer, built by a finance professor. You are not the product — Torv is.

See the full appExplore with sample data. When you link your own, the first 6 months are free, no card required.
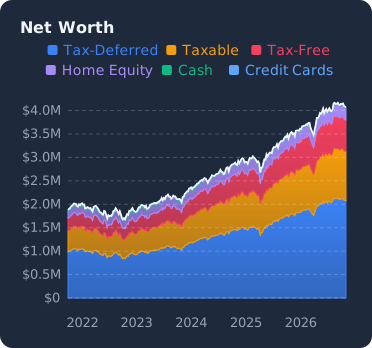
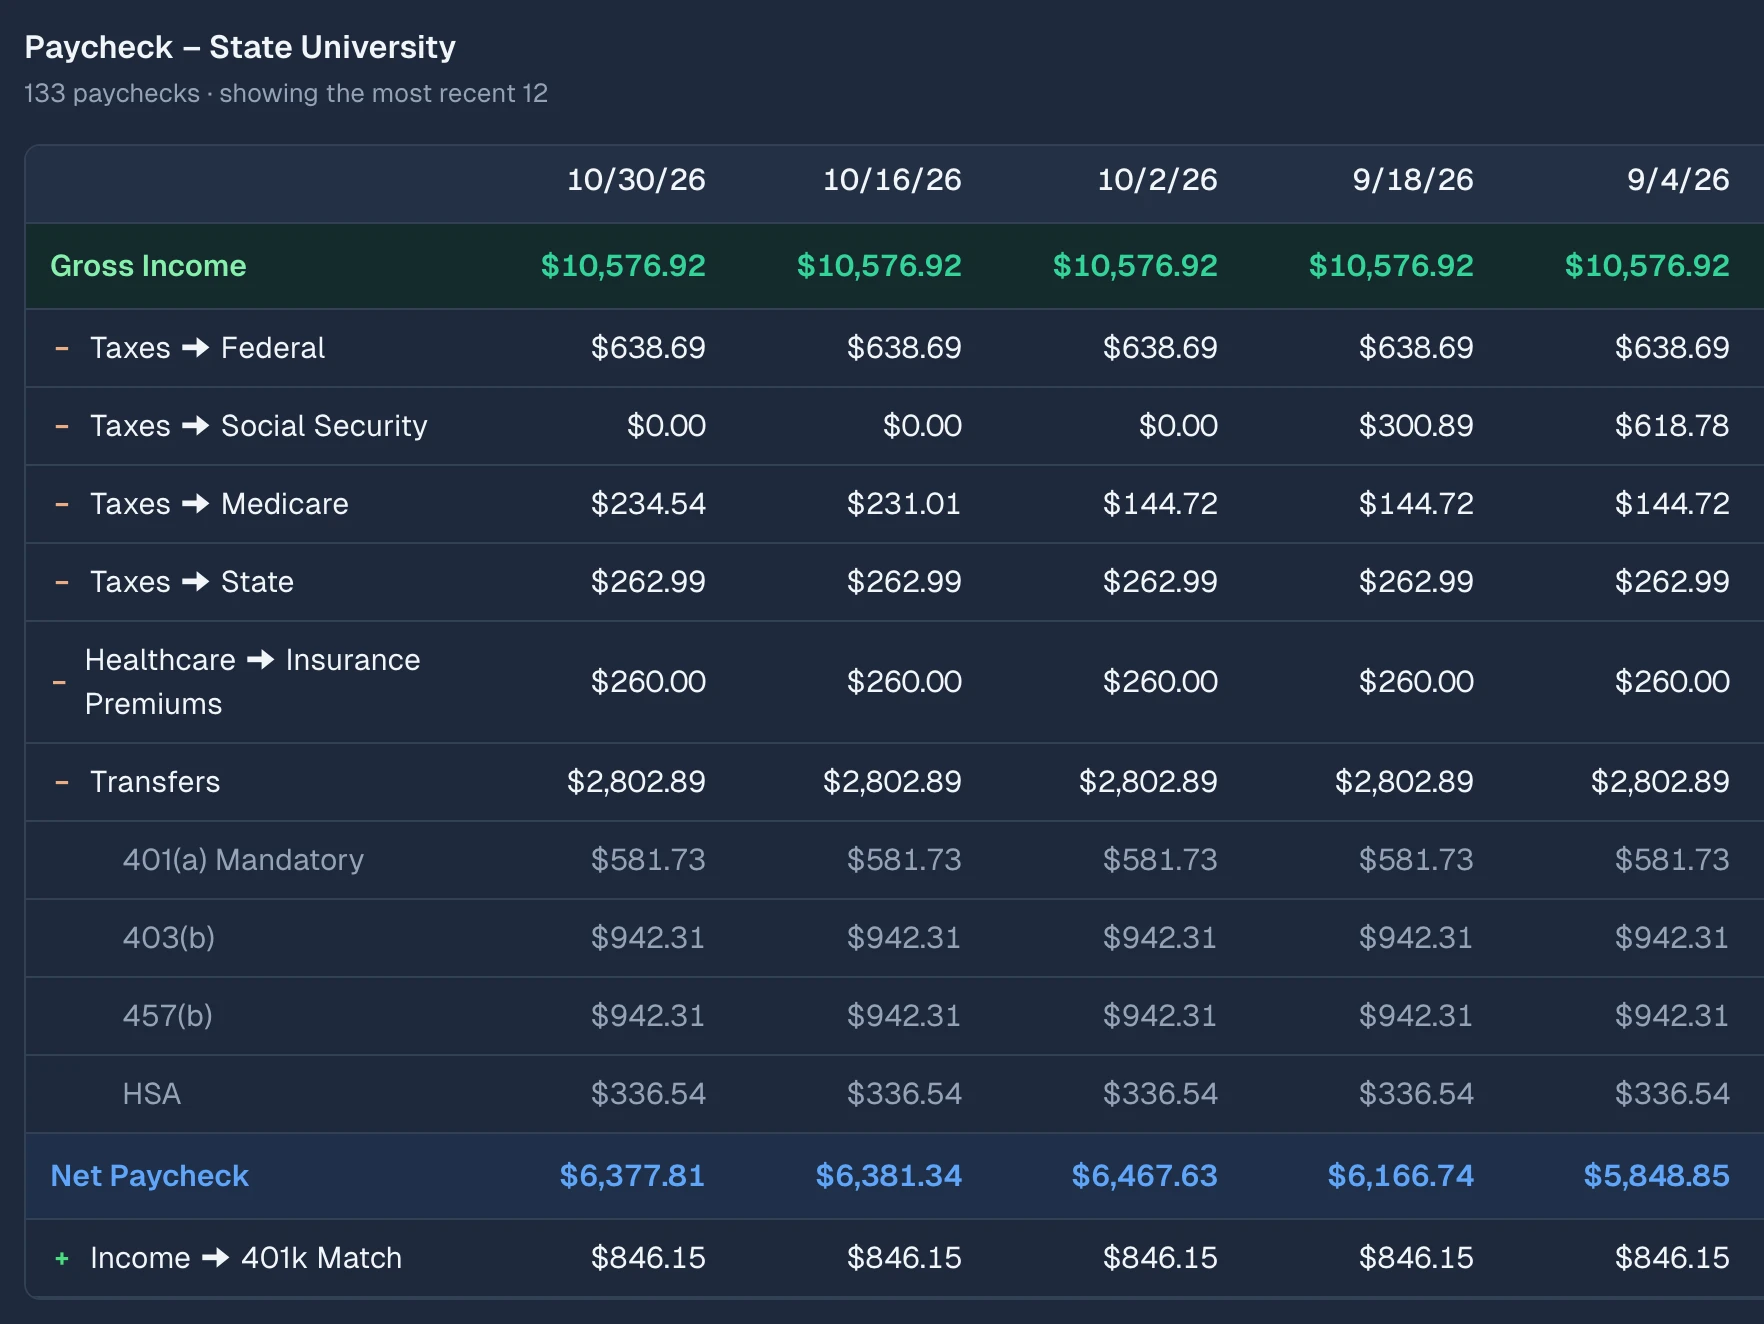
The Torv dashboard for a sample household: net worth, the month's change in net worth broken into savings and capital gains with every penny accounted for, portfolio value, and monthly spending by category.

Your statements, your taxes and the rest of your life, in one place.

The same work a CFO does for a company: keep the books, know the tax cost of every decision, and plan for retirement.

Statements

Every penny accounted for.

Link your banks, cards, brokerages and loans, and Torv keeps your books. Most apps add up your transactions and stop. Torv checks its work: every month, what you earned, spent and gained has to explain the change in your actual balances. If a dollar is missing, Torv tells you.

  • Balance sheet, income statement and cash flows
  • Categorize once, automated forever
  • Net worth history across every account
See statements in the demo
Torv's monthly statements for a sample household, four months side by side: retirement contributions, balance sheet, income statement, statement of cash flows and the decomposition of the change in net worth, with every penny accounted for in every month.

Taxes

The tax rate on your next dollar.

Your tax return, running all year. Torv builds it from your real paychecks, interest and dividends, so you see what you owe before April and what your next dollar really costs.

  • Your W-2, estimated from your paychecks so far
  • Your 1099 interest and dividends, estimated from what's been paid
  • Your Schedule C, from the categories you pick
  • How much more to withhold this year to avoid a penalty
  • IRMAA, capital gains and phase-outs included
See taxes in the demo
Torv's marginal tax rate chart for a sample household: federal, state, Social Security, Medicare and investment tax stacked at every wage level, with the household at $275,000 paying 28.9% on its next dollar.

Retirement

A lifetime plan, solved as one problem.

Roth or Traditional depends on your tax rate later. That rate depends on when you claim Social Security and which accounts you draw down first, and those depend on the Roth conversions you made. Torv solves all of it together, every year to the end of the plan, with no market predictions.

  • Savings order across 401(k), IRA, HSA and brokerage
  • Roth conversions in the gap years
  • Social Security claiming age and withdrawal order
See retirement in the demo
Torv's solved retirement plan for a sample household: account balances by age, from retirement at 46 to 96, stacked by Traditional 401(a)/403(b), Traditional 457(b), Roth 457(b), Roth IRA, HSA, brokerage and 529.

Also in Torv

Plus every transaction in one list, filed automatically, with Torv asking only about the few it cannot place; fully customizable categories; and an opt-in list of recurring charges with their yearly cost.

You are not the product. Torv is.

No sales, no advising, no assets-under-management pitches, no conflicts of interest: just your data and the math. Torv makes money one way, subscriptions. No ads, no data sales, no commissions or referral fees, and nobody’s going to call you: Torv doesn’t have your number.

Each piece of Torv exists somewhere: a budgeting app, a tax calculator, a retirement planner, a portfolio tracker. Nowhere else do they all live in one app, on one set of books, built to the same standard. That is the whole point: the statements feed the tax math, the tax math feeds the plan, and every number agrees with every other.

Statements you can audit.
Real books from your own accounts, kept the way a company keeps its own: an income statement, a balance sheet and a statement of cash flows. Every row opens into the rows behind it, and nothing is hidden or smoothed over.
Built from first principles.
Torv starts from the accounting and the tax code and works outward. It is not a budgeting app with features bolted on, and nothing in it depends on predicting markets.
Tax and planning insight.
A 50-state tax engine shows the marginal rate on your next dollar. The optimizer solves Roth conversions, Social Security timing and withdrawal order together, and ranks the alternatives against each other. Both are free, with or without a subscription; the subscription pays for the bookkeeping: synced accounts, statements with every penny accounted for, and categorization.
From the founder, a finance PhD and professor.

For ten years I tracked my family’s money the way a company tracks its own: every account, every transaction, every month balanced. The tax and retirement math I needed didn’t exist, so I built it.

A breach can’t leak what Torv never had.

The strongest protection isn’t encrypting data. It’s never receiving it.

What Torv Never Has

  • The ability to move money

    Torv is read-only by design. There is no code path that starts a transfer, payment or trade, so the capability can't be stolen or abused.

  • Your bank login

    Connecting an account is handled by Finicity (a Mastercard company) or MX, never by a form on Torv. Torv never sees your username or password.

  • Full account or routing numbers

    Torv asks its data providers for the last 4 digits only, so you can tell your accounts apart, and stores even those encrypted.

  • Your SSN, birth date, street address or last name

    Planning uses your birth year and the state you file taxes in. Sign-up is an email and a password; Torv never asks for a last name.

What Torv Encrypts

Sealed with AES-256-GCM before it reaches the database, with the key kept outside it. Your account is filed under a random ID, not your email.

  • Your email
  • Account names, and the nickname or initials you choose for each person
  • Which institution holds each account
  • The description, merchant and note on every transaction
  • Two-factor secrets and recovery codes
user_idnamebalance
a1b2…7d6cenc:3a7f1b…$47,832.19
a1b2…7d6cenc:5c8d2e…$312,457.83

Example rows with placeholder values, in the shape Torv stores them. Amber is encrypted, blue is the random ID.

No trackers, ads or data sales

You are not the product. Torv makes money from subscriptions, and only from subscriptions.

Full security architecture

Where Torv Fits

FeatureBudgeting Apps*Torv
Free
Torv
$49.99/yr
Lifetime projection on return assumptions you setSome✓✓
Savings & withdrawal sequencing—✓✓
Roth conversion strategy—✓✓
Tax cliffs (Medicare, health subsidy, Social Security)—✓✓
Social Security optimization—✓✓
1040 tax breakdown (federal + state, line by line)—✓✓
This year's tax from your actual paychecks and accounts——✓
Statements with every penny accounted for——✓
Bank & investment account syncing✓—✓
Automatic transaction categorization✓—✓
Spending analysis + trends✓—✓
Recurring charges & price-hike alertsSome—✓
Cash flow forecastingSome—✓
Price$100–200/yrfree$49.99/yr
FeatureRetirement Planners†Torv
$49.99/yr
Lifetime projection on return assumptions you set✓✓
Roth conversion & Social Security comparisons✓✓
One optimizer picks conversions, claiming age and withdrawal order togetherSome✓
Federal + state tax, line by lineSome✓
This year's tax from your actual paychecks and accounts—✓
Linked accounts keep balances currentSome✓
Transactions categorized from linked accounts—✓
Statements with every penny accounted for—✓
Price$99–168/yr$49.99/yr
Show footnotes

* Budgeting Apps includes Monarch, YNAB, Copilot Money, and similar personal finance trackers. They are built around spending: syncing accounts, categorizing transactions, budgeting. Monarch Plus adds a forecast of net worth and retirement from the income, expenses and life events you enter. That is a projection of your own guesses. Torv runs a tax-aware optimizer over Roth conversions, Social Security claiming and withdrawal order, computes the federal and state return line by line, and keeps statements with every penny accounted for. Recurring charge detection and cash flow forecasting vary by app.

† Retirement Planners includes Boldin (formerly NewRetirement), ProjectionLab and Pralana. They plan: each models Roth conversions and Social Security claiming on return assumptions you set, and Pralana sets conversion amounts to a tax-bracket or IRMAA target. Taxes: Pralana says it calculates detailed federal and state income tax, Boldin projects federal and state tax, ProjectionLab estimates tax. Linked accounts: Boldin links accounts for balances but not transactions; ProjectionLab and Pralana take balances by hand (ProjectionLab also by plugin). None turns linked accounts into statements with every penny accounted for.

Prices as published by each vendor, checked October 31, 2026: Monarch Core $99.99/yr, Monarch Plus $199.99/yr, YNAB $109/yr, Copilot Money $109/yr; Pralana $99/yr, ProjectionLab Premium $129/yr, Boldin PlannerPlus $168/yr. Some offer free tiers with fewer features. Torv’s $49.99/yr is one price, and there is no higher tier.

Pricing

Free Tools

No account, no card, no time limit.

Saved in your browser; a free account keeps your inputs on any device.

  • Tax calculator: your full return, federal and state, all 50 states and DC
  • Retirement planner: savings order, Roth conversions, Social Security and withdrawal order, solved together

Torv

$49.99 a year
after a 6-month free trial, no card required
The free tools, plus:
  • Link your accounts — banks, brokerages, loans
  • Income statement, balance sheet, cash flow — to the penny
  • Categorize once, automated forever
  • Every hidden investment fee, exposed
  • Recurring charges and price hikes
  • Net worth history across all accounts
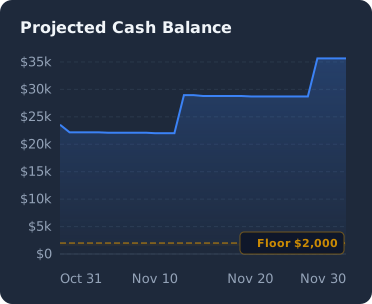
  • Cash forecast
  • Subscribe on torv.app for $49.99 a year and use it everywhere: web, Android, and the iPhone app, at no extra cost.
  • Couples share one subscription, each with their own login.

Need to cancel but can’t sign in? Manage your subscription

Questions

What does Torv cost?

Subscribe on torv.app for $49.99 a year and use it everywhere: web, Android, and the iPhone app, at no extra cost. It starts with a 6-month free trial, no card required. Couples share one subscription, each with their own login. The iPhone app, when it is available, also sells its own subscription at $59.99 a year through Apple (due to Apple App Store fees). The free tax calculator and retirement planner need no account: what you type is saved in your browser, and a free account keeps it on Torv’s servers so it follows you to any device.

Is there a phone app?

Yes, on Android: get it on Google Play. The iPhone app is coming soon. Torv also works in any phone browser, with nothing to install.

How do I cancel?

In Torv, open Account and choose Manage. Need to cancel but can’t sign in? Manage your subscription with your email address. A subscription bought through Apple is managed in iPhone Settings.

Is the data real-time?

Balances and transactions arrive through the same aggregators every app uses. For most institutions a balance shows up the same day or the next, and transactions within two days. Fidelity is the exception: it delivers to Torv about two to three days behind. Torv never papers over that: Accounts show the day each institution last reported a balance, and investment accounts are valued at the latest market close between reports, wherever a holding has a market price. A 6-month free trial is long enough to see how your own institutions behave before you pay anything.

Which accounts can I link?

Banks, credit cards, brokerages and loans, through Finicity and MX. Your bank login goes to them, never to Torv’s servers. How Torv stores your data.

Should I do Roth or Traditional?

Take a couple with most of their savings in a 401(k), retiring at 55 in a state with no income tax. Until Social Security starts, their taxable income can be close to zero, so those years can convert to Roth at 10 or 12 percent, and Traditional contributions saved at 24 percent today can come out cheaper. Torv weighs your rate now against the rate your own withdrawals, conversions and Social Security will create later, and solves them together. See it in the demo.

When should I claim Social Security?

Not by break-even age alone. For a married couple where one spouse earned much more, waiting from 62 to 70 makes the larger check roughly three-quarters bigger, and that check is the one the surviving spouse keeps. The waiting years are paid from savings, which also leaves room for low-bracket Roth conversions. Torv tests claiming ages for both of you against your withdrawal order, tax brackets and IRMAA surcharges. See it in the demo.

What about health insurance before Medicare?

Say a couple retires at 60 and buys marketplace coverage until Medicare. The subsidy follows the income on their tax return, not their savings: a year paid mostly from cash and taxable accounts can show low income and a large subsidy, while a big IRA withdrawal or Roth conversion in the same year can shrink it by thousands. Torv plans those years so you stay on the right side of the cliff. See it in the demo.

Ready to see your numbers?